Ho Chi Minh City apartments in Q3: low liquidity, prices hard to fall, supply skewed by segment
Apartment supply in Ho Chi Minh City is concentrated in the high-end segment, with the Q3 absorption rate at only around 25–26%, while primary prices remain high.
Q3 liquidity: absorption only around one quarter of supply
The Q3 reports from two major research firms paint a fairly similar picture: supply has improved, but purchasing power has not kept pace. According to CafeLand, citing a DKRA report published on 12/10, primary supply reached 13,215 units while sales were 3,471 units, an absorption rate of about 26%.
Savills figures published by Báo Xây dựng point in the same direction. Ho Chi Minh City had around 1,900 newly launched units in the quarter, with an absorption rate of 25%. The headline of the article sums up the situation: supply has improved but liquidity remains under pressure.
Although each firm has its own statistical scope and methodology, so the figures cannot be added together or compared in absolute terms, both record an absorption rate of only around 25–26%. In other words, most of the inventory brought to market during the period has not yet found buyers.
- DKRA (via CafeLand): primary supply 13,215 units, sales 3,471 units, absorption 26%.
- Savills (via Báo Xây dựng): around 1,900 newly launched units in Ho Chi Minh City, absorption 25%.
Supply structure tilts heavily toward the high-end segment
A HoREA report sent to the Government in mid-October, according to VnExpress, shows a structural imbalance. High-end and upper-mid-range apartments account for 73.6% of products eligible for capital mobilization since the beginning of the year. The mid-range segment accounts for only 7.1%, and there are no affordable housing projects at all.
The same report states that, as of early September, Ho Chi Minh City had 1,338 projects with prolonged difficulties, with total investment capital of 658084 billion VND. The figure shows that a very large amount of capital is waiting for legal issues to be resolved, and this is one of the reasons new supply struggles to be steadily added to the mass-market segments.
- High-end and upper-mid-range: 73.6% of products eligible for capital mobilization since the beginning of the year.
- Mid-range: 7.1%; affordable: no projects.
- 1,338 projects with difficulties, total capital 658084 billion VND (as of early September).
Primary prices remain high and are forecast to be unlikely to fall sharply
On pricing, VnExpress cites CBRE's Q3 data: the average primary price is about 75 million VND/m² net floor area, excluding VAT and maintenance fund. According to DKRA, the lowest price is 32.8 million VND, the average is 68.5 million VND and the highest is 520.3 million VND/m², including VAT. The two sets of figures differ partly because of how tax is treated and the survey scope, so readers should note the conditions attached to each figure.
On the outlook, CafeF on 13/10 cited Savills' assessment that apartment prices in Ho Chi Minh City are unlikely to fall sharply over the next 6–12 months. This view is consistent with a supply picture skewed toward the high-end segment and prolonged legal bottlenecks, but it remains a forecast by a research firm, not a definitive conclusion.
- CBRE: average 75 million VND/m² net floor area, excluding VAT and maintenance fund.
- DKRA: 32.8 million VND (lowest), 68.5 million VND (average), 520.3 million VND/m² (highest), including VAT.
Perspective for apartment buyers and renters
With a low absorption rate, buyers have more room to negotiate and more time to compare. However, according to Savills' forecast, there is little basis for expecting a deep price drop by waiting. Those buying to live in should prioritize assessing the project's legal status, handover schedule and affordability rather than chasing price rumors.
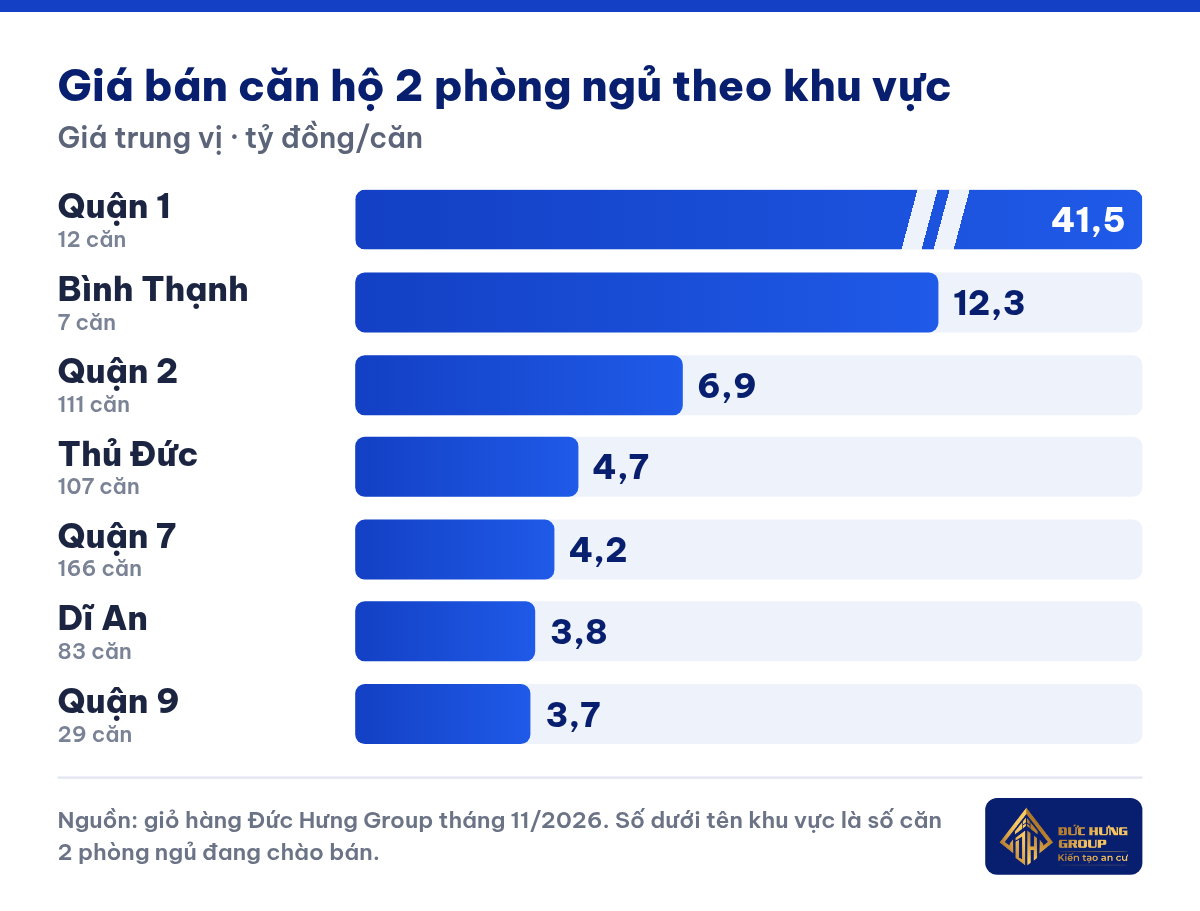
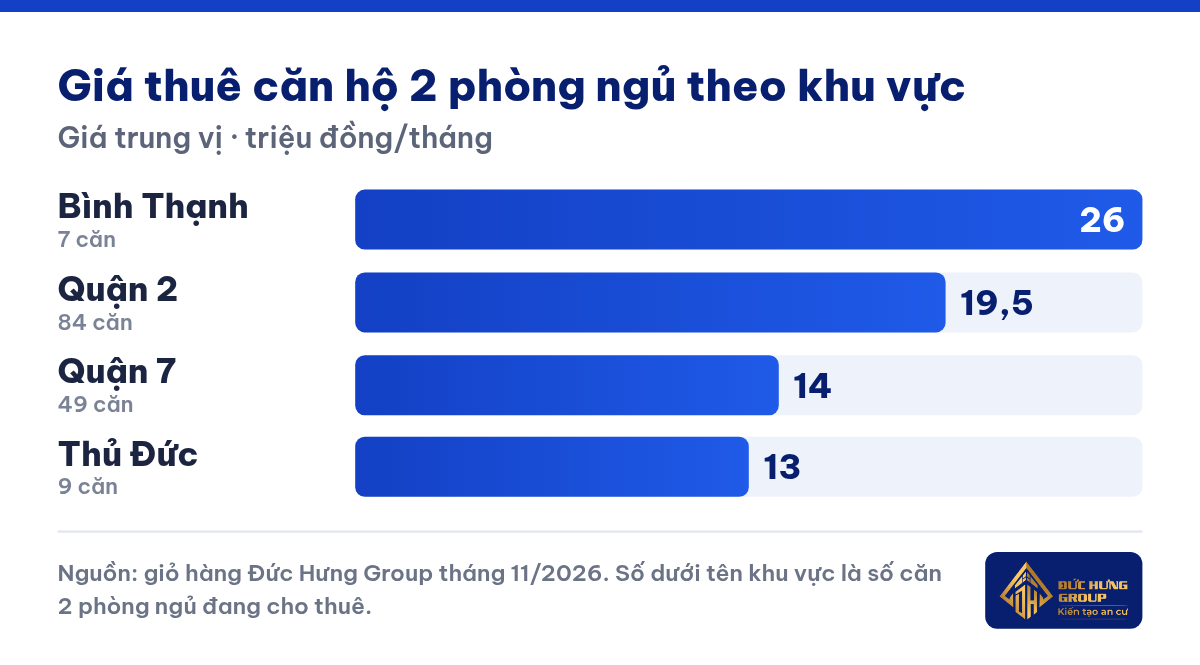
Đức Hưng Group's available-units data for 11/2026 (median price of 2BR apartments) shows clear differences between areas. District 2 has 130 apartments for rent, a median rent of 19.5 million VND/month, and 212 apartments for sale with a median price of 6.9 billion VND. District 7 has 86 apartments for rent at 14 million VND/month and 270 apartments for sale, with a median price of 4.2 billion VND. Thu Duc has a median rent of 13 million VND/month and a sale price of 4.7 billion VND, with 173 apartments for sale. Binh Thanh has a rent of 26 million VND/month and a sale price of 12.3 billion VND, but only 43 apartments for sale.
In the more affordable group, Di An has a median sale price of 3.8 billion VND (103 apartments for sale) and District 9 has 3.7 billion VND (78 apartments for sale); neither area has enough rental samples to calculate a median rent. District 1 has a median sale price of 41.5 billion VND with 20 apartments for sale, and likewise lacks sufficient rental data.
If annual rent is divided by the median sale price, the indicative gross rental yield is roughly 4% in District 7, 3.4% in District 2, 3.3% in Thu Duc and 2.5% in Binh Thanh. This is only an illustrative calculation from the available-units data, before costs, vacancy periods or taxes. Renters can refer to prices by area to balance their budgets; buyers should further compare by floor area, furnishing and the legal status of each unit. Contact Đức Hưng Group for advice tailored to your specific needs.
Frequently asked questions
What was the apartment absorption rate in Ho Chi Minh City in Q3?
According to DKRA via CafeLand, the absorption rate is about 26%; according to Savills via Báo Xây dựng, it is 25%. The two firms have different statistical scopes, so the figures are for reference only.
What are primary apartment prices in Ho Chi Minh City at present?
According to CBRE's Q3 data, the average price is about 75 million VND/m² net floor area, excluding VAT and maintenance fund. According to DKRA, the average price is 68.5 million VND/m², including VAT.